Home  >  Blog  >  Nri corner
An NRI's Guide to Buying Property in Bangalore (2026)
NRI CORNER

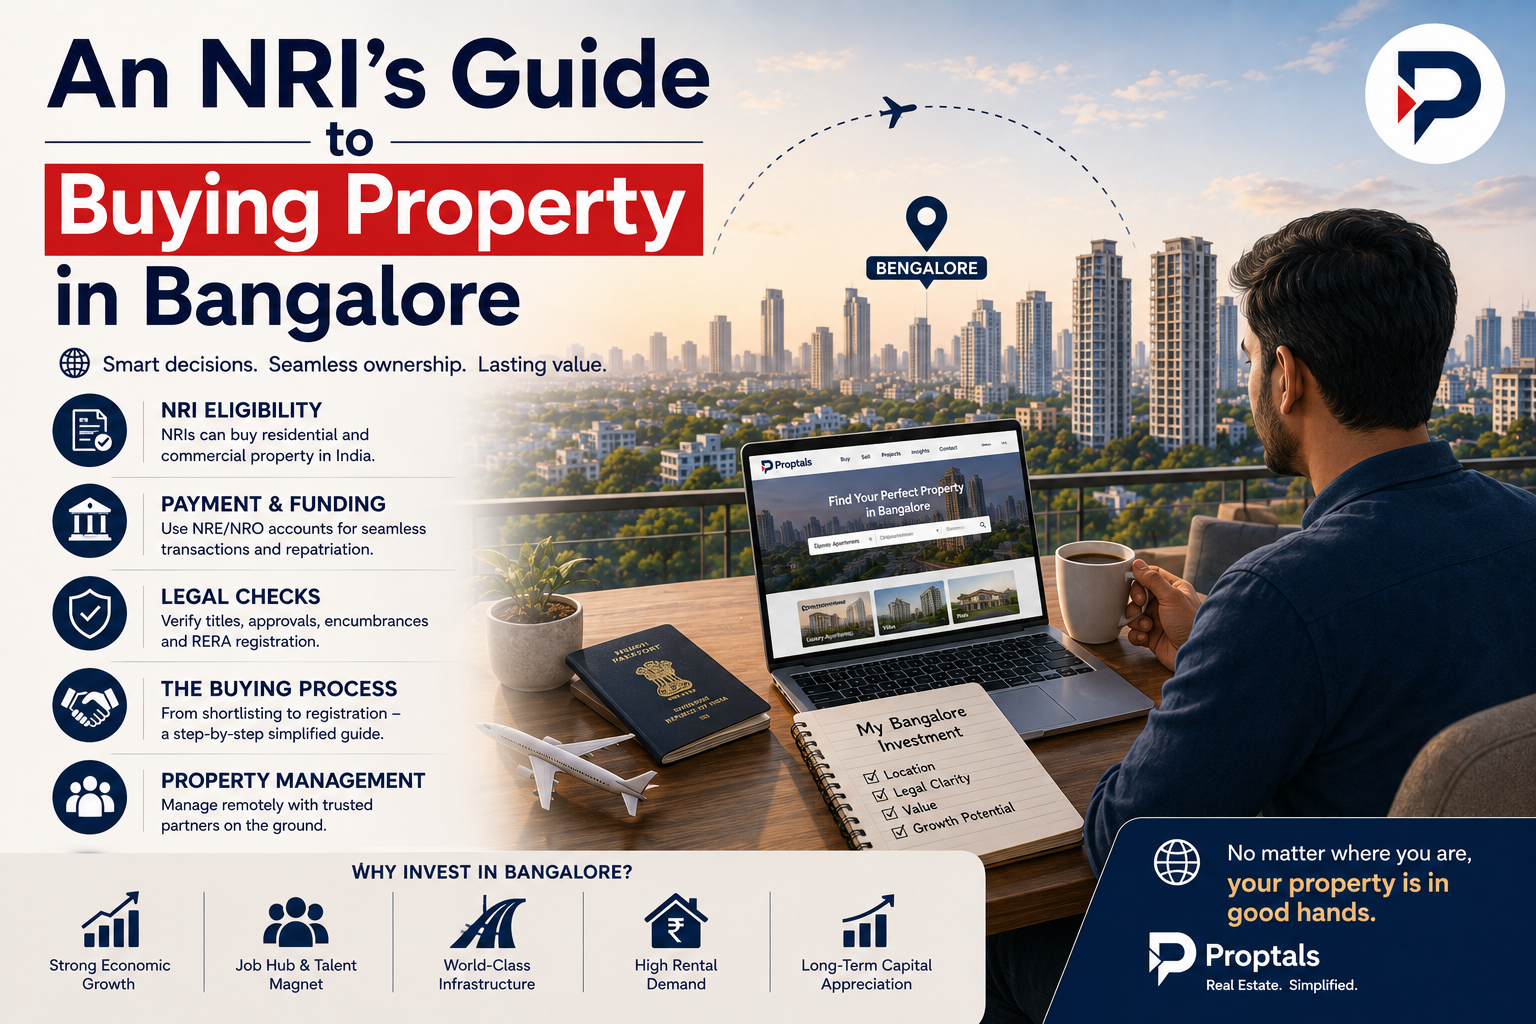
An NRI's Guide to Buying Property in Bangalore (2026)

What NRIs and OCI cardholders can buy in Bangalore, how to pay, what to check, what it costs to register, and what changes when you rent it out or sell. A practical guide from someone who handles these deals on the ground.

Tariq Sallam
By Tariq Sallam, founder of Proptals
Jul 7, 2026 · Updated Oct 1, 2026
10 min read

KEY TAKEAWAYS

  • NRIs and OCI cardholders can buy any number of residential and commercial properties in India. Agricultural land, plantations and farmhouses are off limits unless inherited or gifted.
  • Pay only through Indian banking channels: your NRE, NRO or FCNR account, or an NRI home loan. Cash and payments in foreign currency are not allowed.
  • In Bengaluru, expect 5% stamp duty plus 1% registration fee on most premium homes, and make sure the property has a final e-khata before you pay anything substantial.
  • If you won't be in India, use a specific, registered power of attorney, not a general one.
  • When you rent the home out or later sell it, the tenant or buyer must deduct tax at source. From 1 October 2026 a buyer from an NRI no longer needs a TAN to do this.
  • Most problems come from skipped checks, not bad luck: title, approvals, e-khata, encumbrances and the builder's RERA record.

The story is usually similar. Someone in Dubai, Singapore, London or the Bay Area has decided it is time to own a home in Bangalore, perhaps for retirement, for parents, or as an investment. They have browsed the portals and spoken to a developer's sales team, and now they want someone on the ground to tell them what is real.

This guide is what I tell them. It covers what you are allowed to buy, how the money has to move, the checks that matter in Bangalore specifically, what registration costs, and what happens later when you rent the property out or sell it. Rules change, so treat this as a map, not a substitute for your own chartered accountant and lawyer.

Who Counts as an NRI, and Does OCI Change Anything?

For property purposes, Indian law looks at two things: your residential status for tax, and your nationality. If you are an Indian citizen living abroad, you are a Non-Resident Indian (NRI). If you hold a foreign passport but have an Overseas Citizen of India (OCI) card, you are treated almost identically when it comes to buying property.

In practice, both NRIs and OCI cardholders can buy residential and commercial property in India without any approval from the Reserve Bank of India, and there is no limit on how many properties you own. The same rules apply in Bangalore as anywhere else in the country.

Foreign nationals who are not of Indian origin face much tighter restrictions and generally cannot buy property in India except in narrow cases. If that is your situation, speak to a lawyer before you go any further.

What You Can and Cannot Buy

Property typeCan an NRI or OCI buy it?Notes
Apartments, villas, independent housesYesNo limit on number
Residential plots in approved layoutsYesCheck layout approval and conversion
Offices, shops, commercial spaceYesNo limit on number
Agricultural landNoCan be inherited, or gifted by a resident Indian relative
Plantation propertyNoSame as agricultural land
FarmhousesNoSame as agricultural land

The farmhouse and agricultural land rule catches people out around Bangalore, because so many 'managed farmland' and weekend-home projects are marketed on the city's edges. If the land is still agricultural in the revenue records, an NRI cannot buy it, however it is advertised. A converted plot in an approved layout is a different matter. That is why the conversion order is one of the first documents I ask for.

How the Money Has to Move

Every rupee you pay for the property must come through normal Indian banking channels. In practice that means one of the following:

  • NRE account: money you earned abroad, held in rupees. Fully repatriable.
  • NRO account: income earned in India, such as rent or dividends. Repatriation is capped at USD 1 million per financial year, subject to tax paperwork.
  • FCNR deposit: foreign currency fixed deposits held with an Indian bank.
  • An NRI home loan from an Indian bank or housing finance company.

You cannot pay in foreign currency directly to the seller or developer, and you should never pay any part of the price in cash. Beyond being illegal, an undocumented payment makes it very hard to repatriate your money when you sell, because you cannot prove what you paid.

Keep a clean trail: the bank statements showing each transfer, the receipts from the developer or seller, and the registered sale deed. When you sell years later, your chartered accountant will need all of it.

Financing: NRI Home Loans

Most large Indian banks and housing finance companies lend to NRIs. Lenders typically finance a large share of the property value and expect you to fund the rest from your own money. The exact percentage depends on the loan size, your income, and the lender's current policy.

Expect more paperwork than a resident borrower: passport and visa, overseas employment contract or business documents, salary slips, overseas bank statements, and sometimes a credit report from your country of residence. Many lenders also ask for a local co-applicant or a power of attorney holder in India to handle the paperwork.

EMIs must be paid from your NRE or NRO account, or through funds remitted from abroad. Start the loan conversation early. Getting sanction in principle before you commit to a property gives you negotiating strength and avoids a scramble later.

Buying in Bangalore: The Checks That Matter Most

The legal framework is national, but the paperwork is very local. These are the checks I insist on for every NRI purchase in Bangalore.

1. Title and the chain of ownership

A lawyer should trace ownership back over a long period, typically thirty years or more for land, and confirm every transfer is properly documented. Missing links in the chain are the most common reason banks refuse to lend on a property that otherwise looks fine.

2. Final e-khata

In Bengaluru, an e-khata has been mandatory for registering property since October 2024. Property records are now managed under the Greater Bengaluru Authority and its city corporations through the e-Aasthi system. Only a final e-khata, not a draft, is accepted for registration. If the seller does not have one, the sale cannot be registered until it is sorted out. Read our e-khata guide for the details.

3. Encumbrance certificate

The encumbrance certificate shows mortgages, court attachments and earlier transactions registered against the property. Read the whole period, not just recent years.

4. Approvals and occupancy

For apartments and villas, check the sanctioned building plan, the occupancy certificate for completed buildings, and whether what was built matches what was approved. Unapproved floors or deviations can affect your loan, your resale and, in extreme cases, the building itself.

5. RERA registration for new projects

Any under-construction project of a meaningful size must be registered with the Karnataka Real Estate Regulatory Authority. Check the registration on the K-RERA website, read the developer's quarterly progress updates, and compare the promised completion date with what you see on site.

6. A written title opinion

An independent lawyer's written opinion costs very little compared with the value of the property. If a bank is lending, it will do its own legal check too, but do not rely on the bank alone: its job is to protect the bank.

The Buying Process, Step by Step

  1. Brief. Budget, preferred areas, size, timeline, whether you will live in it, rent it or hold it for family.
  2. Shortlist. Three to five options visited on your behalf, with photos, video walkthroughs and honest notes.
  3. Due diligence. Documents collected and reviewed by a lawyer before any large payment.
  4. Booking and agreement. A token or booking amount, then an agreement for sale that sets the price, payment schedule and timelines.
  5. Loan. Sanction, valuation and legal check by the lender, then disbursement directly to the seller or developer.
  6. Registration. The sale deed is registered at the sub-registrar's office, by you in person or by your power of attorney holder.
  7. After registration. Khata transfer into your name, utility connections, and if you are renting it out, a tenant and a management arrangement.

Power of Attorney: Buying Without Flying In

Many NRIs complete the entire purchase without travelling, by appointing someone in India under a power of attorney. A parent, sibling or trusted friend is usual.

Keep it specific: name the property, the transaction and the exact powers granted, such as signing the agreement, paying from a named account and registering the deed. Avoid a general power of attorney that lets someone do anything with your assets.

A power of attorney signed abroad usually has to be executed before an Indian embassy or consulate, or notarised and apostilled depending on the country, and then adjudicated for stamp duty in Karnataka within the prescribed time after it arrives in India. Your lawyer will tell you the exact process for the country you live in.

What It Costs to Register in Bengaluru

On top of the agreed price, budget for government charges and professional fees. For most premium homes in Bengaluru, the main costs are:

CostTypical amount
Stamp duty5% of the property value for properties above ₹45 lakh
Registration fee1% of the property value
GST (under-construction homes only)Charged by the developer on the price; ready homes with an occupancy certificate do not attract GST
Legal feesFor title checks, agreements and registration
BrokerageAgreed in writing; on new projects where we are the developer's partner, the developer pays us

Stamp duty is calculated on the higher of the agreement value and the government guidance value. Lower rates apply to cheaper properties, but most homes in the premium segment fall into the top slab. Always check current rates on the state's Kaveri portal before you budget.

Renting It Out While You Live Abroad

Most NRI buyers rent the home out for a few years. A few things to set up properly:

  • Rent goes into your NRO account. It is taxable in India even though you live abroad.
  • The tenant must deduct tax at source on rent paid to a non-resident landlord and deposit it with the government. Corporate tenants are strict about this; individual tenants often are not, which can create problems for both of you.
  • A registered rental agreement, a move-in inventory with photos, and police verification of the tenant.
  • Someone local to deal with repairs, society notices and renewals. This is what property management is for.

Selling Later: Tax and Getting Your Money Out

When an NRI sells property in India, the buyer must deduct tax at source from the payment. The rate depends on how long you held the property: gains on property held for more than 24 months are long-term, and TDS on those is currently 12.5% plus applicable surcharge and cess. Short-term gains attract a much higher rate.

The deduction is calculated on the sale price by default, not on your actual gain, which often means far more tax is withheld than you owe. You can apply to the income tax department for a lower deduction certificate before the sale, based on your real capital gain. It takes time, so start early.

From 1 October 2026, a resident buyer purchasing from an NRI no longer needs a separate TAN to deduct and deposit this tax. They can use their PAN and a simpler challan, as they would for a resident seller. This removes one of the most common reasons buyers hesitated to deal with NRI sellers.

After tax, sale proceeds can generally be repatriated. If the property was bought with money from abroad or your NRE account, repatriation of the original investment is straightforward for up to two residential properties. Proceeds held in your NRO account fall within the USD 1 million per financial year limit, with a chartered accountant's certificate and the bank's forms.

Mistakes I See Most Often

  • Buying 'farmland' or a farmhouse that NRIs are not allowed to own.
  • Paying a large booking amount before a lawyer has seen the documents.
  • Signing a general power of attorney instead of a specific one.
  • Assuming the developer's sales team will flag problems with their own project.
  • Letting a tenant skip TDS, then facing a tax notice later.
  • Not keeping the paper trail needed to repatriate money when selling.

Frequently Asked Questions

Can an NRI buy property in Bangalore without visiting India?

Yes. With a specific, registered power of attorney, someone you trust in India can sign the agreement and register the sale deed for you. Viewings can be done by video, with a local advisor visiting in person.

Can OCI cardholders buy property in India?

Yes. OCI cardholders can buy residential and commercial property on the same terms as NRIs. Like NRIs, they cannot buy agricultural land, plantations or farmhouses, except by inheritance or gift.

Can I pay for an Indian property from my overseas bank account?

Not directly in foreign currency. Remit the money to your NRE or FCNR account in India first, or take an NRI home loan, and pay from there.

How much is stamp duty in Bangalore?

For properties above ₹45 lakh, stamp duty in Karnataka is 5% of the property value, plus a 1% registration fee. Check the current rates on the Kaveri portal before you budget.

Do I need an e-khata to buy property in Bengaluru?

Yes. Since October 2024, a final e-khata has been mandatory for registering property in Bengaluru. Make sure the seller has one before you pay anything substantial.

How much tax is deducted when an NRI sells property?

For property held over 24 months, TDS is currently 12.5% plus surcharge and cess, calculated on the sale value unless you obtain a lower deduction certificate based on your actual gain. Speak to a chartered accountant before you sell.

Buying in Bangalore from abroad is very doable. The NRIs who have a good experience are the ones who slow down at the document stage, keep the money trail clean, and have someone on the ground they trust. If you would like a second opinion on a property you are considering, send me a WhatsApp.

Sources

Last updated Oct 1, 2026. Figures and rules change; check current details with a professional before you act.

Share this post:
Tariq Sallam, Founder of Proptals
ABOUT THE AUTHOR
Tariq Sallam
Founder, Proptals · Karnataka RERA registered agent

Tariq has advised buyers, sellers, landlords, landowners and developers in Bangalore since 2004. He writes about what he sees on site visits, in negotiations and at registration offices.

ASK TARIQ ON WHATSAPP
An NRI's Guide to Buying Property in Bangalore (2026) | Proptals Blog
Home  >  Blog  >  Nri corner
An NRI's Guide to Buying Property in Bangalore (2026)
NRI CORNER

An NRI's Guide to Buying Property in Bangalore (2026)

What NRIs and OCI cardholders can buy in Bangalore, how to pay, what to check, what it costs to register, and what changes when you rent it out or sell. A practical guide from someone who handles these deals on the ground.

Tariq Sallam
By Tariq Sallam, founder of Proptals
Jul 7, 2026 · Updated Oct 1, 2026
10 min read

KEY TAKEAWAYS

  • NRIs and OCI cardholders can buy any number of residential and commercial properties in India. Agricultural land, plantations and farmhouses are off limits unless inherited or gifted.
  • Pay only through Indian banking channels: your NRE, NRO or FCNR account, or an NRI home loan. Cash and payments in foreign currency are not allowed.
  • In Bengaluru, expect 5% stamp duty plus 1% registration fee on most premium homes, and make sure the property has a final e-khata before you pay anything substantial.
  • If you won't be in India, use a specific, registered power of attorney, not a general one.
  • When you rent the home out or later sell it, the tenant or buyer must deduct tax at source. From 1 October 2026 a buyer from an NRI no longer needs a TAN to do this.
  • Most problems come from skipped checks, not bad luck: title, approvals, e-khata, encumbrances and the builder's RERA record.

The story is usually similar. Someone in Dubai, Singapore, London or the Bay Area has decided it is time to own a home in Bangalore, perhaps for retirement, for parents, or as an investment. They have browsed the portals and spoken to a developer's sales team, and now they want someone on the ground to tell them what is real.

This guide is what I tell them. It covers what you are allowed to buy, how the money has to move, the checks that matter in Bangalore specifically, what registration costs, and what happens later when you rent the property out or sell it. Rules change, so treat this as a map, not a substitute for your own chartered accountant and lawyer.

Who Counts as an NRI, and Does OCI Change Anything?

For property purposes, Indian law looks at two things: your residential status for tax, and your nationality. If you are an Indian citizen living abroad, you are a Non-Resident Indian (NRI). If you hold a foreign passport but have an Overseas Citizen of India (OCI) card, you are treated almost identically when it comes to buying property.

In practice, both NRIs and OCI cardholders can buy residential and commercial property in India without any approval from the Reserve Bank of India, and there is no limit on how many properties you own. The same rules apply in Bangalore as anywhere else in the country.

Foreign nationals who are not of Indian origin face much tighter restrictions and generally cannot buy property in India except in narrow cases. If that is your situation, speak to a lawyer before you go any further.

What You Can and Cannot Buy

Property typeCan an NRI or OCI buy it?Notes
Apartments, villas, independent housesYesNo limit on number
Residential plots in approved layoutsYesCheck layout approval and conversion
Offices, shops, commercial spaceYesNo limit on number
Agricultural landNoCan be inherited, or gifted by a resident Indian relative
Plantation propertyNoSame as agricultural land
FarmhousesNoSame as agricultural land

The farmhouse and agricultural land rule catches people out around Bangalore, because so many 'managed farmland' and weekend-home projects are marketed on the city's edges. If the land is still agricultural in the revenue records, an NRI cannot buy it, however it is advertised. A converted plot in an approved layout is a different matter. That is why the conversion order is one of the first documents I ask for.

How the Money Has to Move

Every rupee you pay for the property must come through normal Indian banking channels. In practice that means one of the following:

  • NRE account: money you earned abroad, held in rupees. Fully repatriable.
  • NRO account: income earned in India, such as rent or dividends. Repatriation is capped at USD 1 million per financial year, subject to tax paperwork.
  • FCNR deposit: foreign currency fixed deposits held with an Indian bank.
  • An NRI home loan from an Indian bank or housing finance company.

You cannot pay in foreign currency directly to the seller or developer, and you should never pay any part of the price in cash. Beyond being illegal, an undocumented payment makes it very hard to repatriate your money when you sell, because you cannot prove what you paid.

Keep a clean trail: the bank statements showing each transfer, the receipts from the developer or seller, and the registered sale deed. When you sell years later, your chartered accountant will need all of it.

Financing: NRI Home Loans

Most large Indian banks and housing finance companies lend to NRIs. Lenders typically finance a large share of the property value and expect you to fund the rest from your own money. The exact percentage depends on the loan size, your income, and the lender's current policy.

Expect more paperwork than a resident borrower: passport and visa, overseas employment contract or business documents, salary slips, overseas bank statements, and sometimes a credit report from your country of residence. Many lenders also ask for a local co-applicant or a power of attorney holder in India to handle the paperwork.

EMIs must be paid from your NRE or NRO account, or through funds remitted from abroad. Start the loan conversation early. Getting sanction in principle before you commit to a property gives you negotiating strength and avoids a scramble later.

Buying in Bangalore: The Checks That Matter Most

The legal framework is national, but the paperwork is very local. These are the checks I insist on for every NRI purchase in Bangalore.

1. Title and the chain of ownership

A lawyer should trace ownership back over a long period, typically thirty years or more for land, and confirm every transfer is properly documented. Missing links in the chain are the most common reason banks refuse to lend on a property that otherwise looks fine.

2. Final e-khata

In Bengaluru, an e-khata has been mandatory for registering property since October 2024. Property records are now managed under the Greater Bengaluru Authority and its city corporations through the e-Aasthi system. Only a final e-khata, not a draft, is accepted for registration. If the seller does not have one, the sale cannot be registered until it is sorted out. Read our e-khata guide for the details.

3. Encumbrance certificate

The encumbrance certificate shows mortgages, court attachments and earlier transactions registered against the property. Read the whole period, not just recent years.

4. Approvals and occupancy

For apartments and villas, check the sanctioned building plan, the occupancy certificate for completed buildings, and whether what was built matches what was approved. Unapproved floors or deviations can affect your loan, your resale and, in extreme cases, the building itself.

5. RERA registration for new projects

Any under-construction project of a meaningful size must be registered with the Karnataka Real Estate Regulatory Authority. Check the registration on the K-RERA website, read the developer's quarterly progress updates, and compare the promised completion date with what you see on site.

6. A written title opinion

An independent lawyer's written opinion costs very little compared with the value of the property. If a bank is lending, it will do its own legal check too, but do not rely on the bank alone: its job is to protect the bank.

The Buying Process, Step by Step

  1. Brief. Budget, preferred areas, size, timeline, whether you will live in it, rent it or hold it for family.
  2. Shortlist. Three to five options visited on your behalf, with photos, video walkthroughs and honest notes.
  3. Due diligence. Documents collected and reviewed by a lawyer before any large payment.
  4. Booking and agreement. A token or booking amount, then an agreement for sale that sets the price, payment schedule and timelines.
  5. Loan. Sanction, valuation and legal check by the lender, then disbursement directly to the seller or developer.
  6. Registration. The sale deed is registered at the sub-registrar's office, by you in person or by your power of attorney holder.
  7. After registration. Khata transfer into your name, utility connections, and if you are renting it out, a tenant and a management arrangement.

Power of Attorney: Buying Without Flying In

Many NRIs complete the entire purchase without travelling, by appointing someone in India under a power of attorney. A parent, sibling or trusted friend is usual.

Keep it specific: name the property, the transaction and the exact powers granted, such as signing the agreement, paying from a named account and registering the deed. Avoid a general power of attorney that lets someone do anything with your assets.

A power of attorney signed abroad usually has to be executed before an Indian embassy or consulate, or notarised and apostilled depending on the country, and then adjudicated for stamp duty in Karnataka within the prescribed time after it arrives in India. Your lawyer will tell you the exact process for the country you live in.

What It Costs to Register in Bengaluru

On top of the agreed price, budget for government charges and professional fees. For most premium homes in Bengaluru, the main costs are:

CostTypical amount
Stamp duty5% of the property value for properties above ₹45 lakh
Registration fee1% of the property value
GST (under-construction homes only)Charged by the developer on the price; ready homes with an occupancy certificate do not attract GST
Legal feesFor title checks, agreements and registration
BrokerageAgreed in writing; on new projects where we are the developer's partner, the developer pays us

Stamp duty is calculated on the higher of the agreement value and the government guidance value. Lower rates apply to cheaper properties, but most homes in the premium segment fall into the top slab. Always check current rates on the state's Kaveri portal before you budget.

Renting It Out While You Live Abroad

Most NRI buyers rent the home out for a few years. A few things to set up properly:

  • Rent goes into your NRO account. It is taxable in India even though you live abroad.
  • The tenant must deduct tax at source on rent paid to a non-resident landlord and deposit it with the government. Corporate tenants are strict about this; individual tenants often are not, which can create problems for both of you.
  • A registered rental agreement, a move-in inventory with photos, and police verification of the tenant.
  • Someone local to deal with repairs, society notices and renewals. This is what property management is for.

Selling Later: Tax and Getting Your Money Out

When an NRI sells property in India, the buyer must deduct tax at source from the payment. The rate depends on how long you held the property: gains on property held for more than 24 months are long-term, and TDS on those is currently 12.5% plus applicable surcharge and cess. Short-term gains attract a much higher rate.

The deduction is calculated on the sale price by default, not on your actual gain, which often means far more tax is withheld than you owe. You can apply to the income tax department for a lower deduction certificate before the sale, based on your real capital gain. It takes time, so start early.

From 1 October 2026, a resident buyer purchasing from an NRI no longer needs a separate TAN to deduct and deposit this tax. They can use their PAN and a simpler challan, as they would for a resident seller. This removes one of the most common reasons buyers hesitated to deal with NRI sellers.

After tax, sale proceeds can generally be repatriated. If the property was bought with money from abroad or your NRE account, repatriation of the original investment is straightforward for up to two residential properties. Proceeds held in your NRO account fall within the USD 1 million per financial year limit, with a chartered accountant's certificate and the bank's forms.

Mistakes I See Most Often

  • Buying 'farmland' or a farmhouse that NRIs are not allowed to own.
  • Paying a large booking amount before a lawyer has seen the documents.
  • Signing a general power of attorney instead of a specific one.
  • Assuming the developer's sales team will flag problems with their own project.
  • Letting a tenant skip TDS, then facing a tax notice later.
  • Not keeping the paper trail needed to repatriate money when selling.

Frequently Asked Questions

Can an NRI buy property in Bangalore without visiting India?

Yes. With a specific, registered power of attorney, someone you trust in India can sign the agreement and register the sale deed for you. Viewings can be done by video, with a local advisor visiting in person.

Can OCI cardholders buy property in India?

Yes. OCI cardholders can buy residential and commercial property on the same terms as NRIs. Like NRIs, they cannot buy agricultural land, plantations or farmhouses, except by inheritance or gift.

Can I pay for an Indian property from my overseas bank account?

Not directly in foreign currency. Remit the money to your NRE or FCNR account in India first, or take an NRI home loan, and pay from there.

How much is stamp duty in Bangalore?

For properties above ₹45 lakh, stamp duty in Karnataka is 5% of the property value, plus a 1% registration fee. Check the current rates on the Kaveri portal before you budget.

Do I need an e-khata to buy property in Bengaluru?

Yes. Since October 2024, a final e-khata has been mandatory for registering property in Bengaluru. Make sure the seller has one before you pay anything substantial.

How much tax is deducted when an NRI sells property?

For property held over 24 months, TDS is currently 12.5% plus surcharge and cess, calculated on the sale value unless you obtain a lower deduction certificate based on your actual gain. Speak to a chartered accountant before you sell.

Buying in Bangalore from abroad is very doable. The NRIs who have a good experience are the ones who slow down at the document stage, keep the money trail clean, and have someone on the ground they trust. If you would like a second opinion on a property you are considering, send me a WhatsApp.

Sources

Last updated Oct 1, 2026. Figures and rules change; check current details with a professional before you act.

Share this post:
Tariq Sallam, Founder of Proptals
ABOUT THE AUTHOR
Tariq Sallam
Founder, Proptals · Karnataka RERA registered agent

Tariq has advised buyers, sellers, landlords, landowners and developers in Bangalore since 2004. He writes about what he sees on site visits, in negotiations and at registration offices.

ASK TARIQ ON WHATSAPP